
CBDT order on Tax treatment of ex-gratia compensation received under BSNL and MTNL Voluntary Retirement Scheme (VRS), 2019
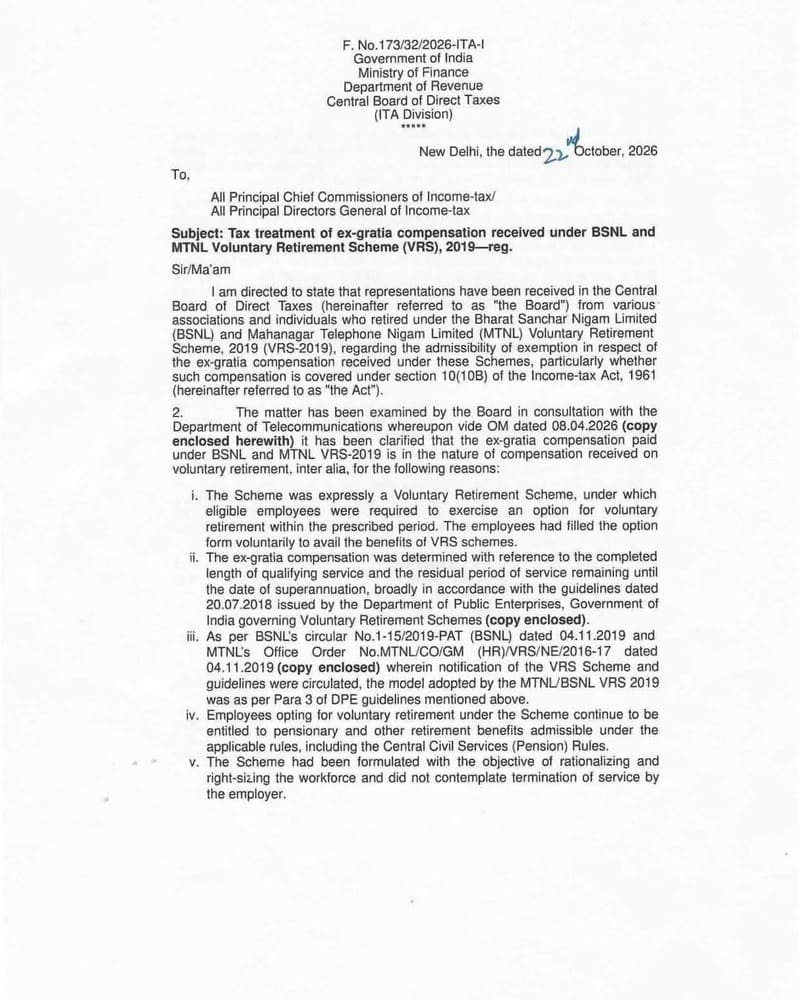
F. No.173/32/2026-ITA-I
Government of India
Ministry of Finance
Department of Revenue
Central Board of Direct Taxes
(ITA Division)
*****
New Delhi, the dated 22nd October, 2026
To,
All Principal Chief Commissioners of Income-tax/
All Principal Directors General of Income-tax
Subject: Tax treatment of ex-gratia compensation received under BSNL and MTNL Voluntary Retirement Scheme (VRS), 2019—reg.
Sir/Ma’am
I am directed to state that representations have been received in the Central Board of Direct Taxes (hereinafter referred to as “the Board”) from various associations and individuals who retired under the Bharat Sanchar Nigam Limited (BSNL) and Mahanagar Telephone Nigam Limited (MTNL) Voluntary Retirement Scheme, 2019 (VRS-2019), regarding the admissibility of exemption in respect of the ex-gratia compensation received under these Schemes, particularly whether such compensation is covered under section 10(10B) of the Income-tax Act, 1961 (hereinafter referred to as “the Act”).
2. The matter has been examined by the Board in consultation with the Department of Telecommunications whereupon vide OM dated 08.04.2026 (copy enclosed herewith) it has been clarified that the ex-gratia compensation paid under BSNL and MTNL VRS-2019 is in the nature of compensation received on voluntary retirement, inter alia, for the following reason:
- The Scheme was expressly a Voluntary Retirement Scheme, under which eligible employees were required to exercise an option for voluntary retirement within the prescribed period. The employees had filled the option form voluntarily to avail the benefits of VRS schemes.
- The ex-gratia compensation was determined with reference to the completed length of qualifying service and the residual period of service remaining until the date of superannuation, broadly in accordance with the guidelines dated 20.07.2018 issued by the Department of Public Enterprises, Government of India governing Voluntary Retirement Schemes (copy enclosed).
- As per BSNL’s circular No.1-15/2019-PAT (BSNL) dated 04.11.2019 and MTNL’s Office Order No.MTNL/CO/GM (HR)/VRS/NE/2016-17 dated 04.11.2019 (copy enclosed) wherein notification of the VRS Scheme and guidelines were circulated, the model adopted by the MTNL/BSNL VRS 2019 was as per Para 3 of DPE guidelines mentioned above.
- Employees opting for voluntary retirement under the Scheme continue to be entitled to pensionary and other retirement benefits admissible under the applicable rules, including the Central Civil Services (Pension) Rules.
- The Scheme had been formulated with the objective of rationalizing and right-sizing the workforce and did not contemplate termination of service by the employer.
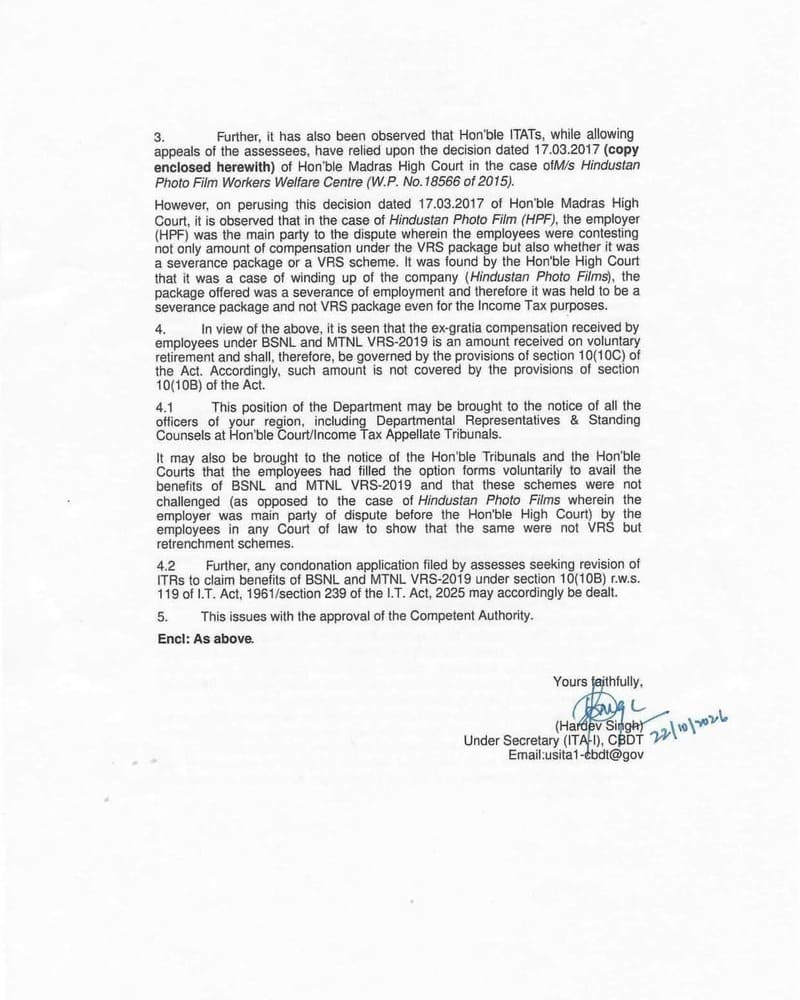
3. Further, it has also been observed that Hon’ble ITATs, while allowing appeals of the assessees, have relied upon the decision dated 17.03.2017 (copy enclosed herewith) of Hon’ble Madras High Court in the case of of M/s Hindustan Photo Film Workers Welfare Centre (W.P. No.18566 of 2015).
However, on perusing this decision dated 17.03.2017 of Hon’ble Madras High Court, it is observed that in the case of Hindustan Photo Film (HPF), the employer (HPF) was the main party to the dispute wherein the employees were contesting not only amount of compensation under the VRS package but also whether it was a severance package or a VRS scheme. It was found by the Hon’ble High Court that it was a case of winding up of the company (Hindustan Photo Films), the package offered was a severance of employment and therefore it was held to be a severance package and not VRS package even for the Income Tax purposes.
4. In view of the above, it is seen that the ex-gratia compensation received by employees under BSNL and MTNL VRS-2019 is an amount received on voluntary retirement and shall, therefore, be governed by the provisions of section 10(10C) of the Act. Accordingly, such amount is not covered by the provisions of section 10(10B) of the Act.
4.1 This position of the Department may be brought to the notice of all the officers of your region, including Departmental Representatives & Standing Counsels at Hon’ble Court/Income Tax Appellate Tribunals.
It may also be brought to the notice of the Hon’ble Tribunals and the Hon’ble Courts that the employees had filled the option forms voluntarily to avail the benefits of BSNL and MTNL VRS-2019 and that these schemes were not challenged (as opposed to the case of Hindustan Photo Films wherein the employer was main party of dispute before the Hon’ble High Court) by the employees in any Court of law to show that the same were not VRS but retrenchment schemes.
4.2 Further, any condonation application filed by assesses seeking revision of ITRs to claim benefits of BSNL and MTNL VRS-2019 under section 10(10B) r.w.s. 119 of I.T. Act, 1961/section 239 of the I.T. Act, 2025 may accordingly be dealt.
5. This issues with the approval of the Competent Authority.
Encl: As above.
Yours faithfully,
Sd/-
(Hardev Singh)
Under Secretary (ITA-I), CBDT
Email: usita1-cbdt[at]gov
Click here to view/download PDF
COMMENTS