
Prevention of Wrongful and Excess payments made to the Governments Servants – Finance Ministry Guidelines vide OM dated 29.09.2026
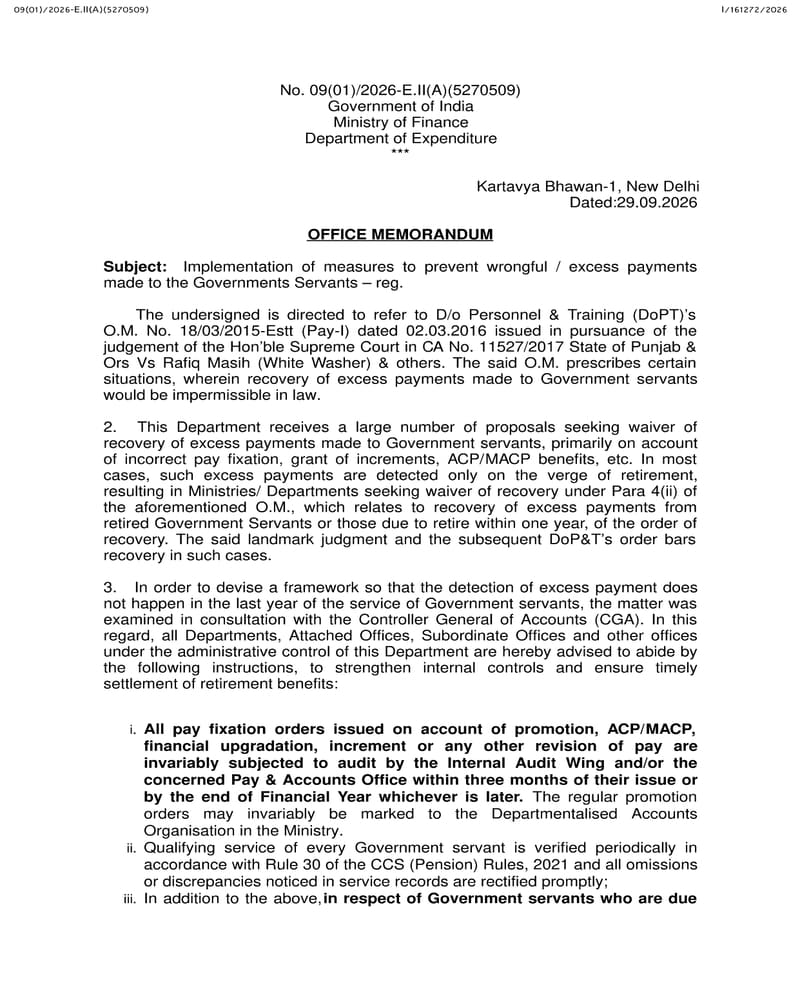
No. 09(01)/2026-E.II(A)(5270509)
Government of India
Ministry of Finance
Department of Expenditure
***
Kartavya Bhawan-1, New Delhi
Dated:29.09.2026
OFFICE MEMORANDUM
Subject: Implementation of measures to prevent wrongful / excess payments made to the Governments Servants – reg.
The undersigned is directed to refer to D/o Personnel & Training (DoPT)’s Ο.Μ. No. 18/03/2015-Estt (Pay- ) dated 02.03.2016 issued in pursuance of the judgement of the Hon’ble Supreme Court in CA No. 11527/2017 State of Punjab & Ors Vs Rafiq Masih (White Washer) & others. The said O.M. prescribes certain situations, wherein recovery of excess payments made to Government servants would be impermissible in law.
2. This Department receives a large number of proposals seeking waiver of recovery of excess payments made to Government servants, primarily on account of incorrect pay fixation, grant of increments, ACP/MACP benefits, etc. In most cases, such excess payments are detected only on the verge of retirement, resulting in Ministries/ Departments seeking waiver of recovery under Para 4(ii) of the aforementioned O.M., which relates to recovery of excess payments from retired Government Servants or those due to retire within one year, of the order of recovery. The said landmark judgment and the subsequent DoP&T’s order bars recovery in such cases.
3. In order to devise a framework so that the detection of excess payment does not happen in the last year of the service of Government servants, the matter was examined in consultation with the Controller General of Accounts (CGA). In this regard, all Departments, Attached Offices, Subordinate Offices and other offices under the administrative control of this Department are hereby advised to abide by the following instructions, to strengthen internal controls and ensure timely settlement of retirement benefits:
- All pay fixation orders issued on account of promotion, ACP/MACP, financial upgradation, increment or any other revision of pay are invariably subjected to audit by the Internal Audit Wing and/or the concerned Pay & Accounts Office within three months of their issue or by the end of Financial Year whichever is later. The regular promotion orders may invariably be marked to the Departmentalised Accounts Organisation in the Ministry.
- Qualifying service of every Government servant is verified periodically in accordance with Rule 30 of the CCS (Pension) Rules, 2021 and all omissions or discrepancies noticed in service records are rectified promptly;
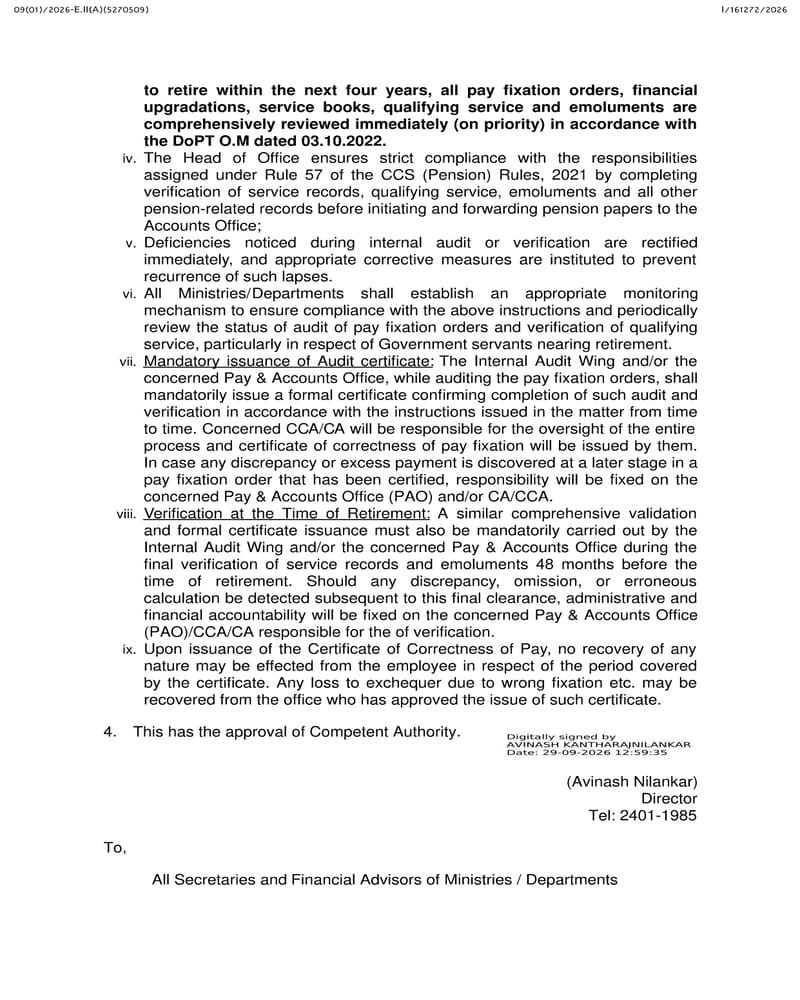
- In addition to the above, in respect of Government servants who are due 1/161272/2026 to retire within the next four years, all pay fixation orders, financial upgradations, service books, qualifying service and emoluments are comprehensively reviewed immediately (on priority) in accordance with the DOPT O.M dated 03.10.2022.
- The Head of Office ensures strict compliance with the responsibilities assigned under Rule 57 of the CCS (Pension) Rules, 2021 by completing verification of service records, qualifying service, emoluments and all other pension-related records before initiating and forwarding pension papers to the Accounts Office;
- Deficiencies noticed during internal audit or verification are rectified immediately, and appropriate corrective measures are instituted to prevent recurrence of such lapses.
- All Ministries/Departments shall establish an appropriate monitoring mechanism to ensure compliance with the above instructions and periodically review the status of audit of pay fixation orders and verification of qualifying service, particularly in respect of Government servants nearing retirement.
- Mandatory issuance of Audit certificate: The Internal Audit Wing and/or the concerned Pay & Accounts Office, while auditing the pay fixation orders, shall mandatorily issue a formal certificate confirming completion of such audit and verification in accordance with the instructions issued in the matter from time to time. Concerned CCA/CA will be responsible for the oversight of the entire process and certificate of correctness of pay fixation will be issued by them. In case any discrepancy or excess payment is discovered at a later stage in a pay fixation order that has been certified, responsibility will be fixed on the concerned Pay & Accounts Office (PAO) and/or CA/CCA.
- Verification at the Time of Retirement: A similar comprehensive validation and formal certificate issuance must also be mandatorily carried out by the Internal Audit Wing and/or the concerned Pay & Accounts Office during the final verification of service records and emoluments 48 months before the time of retirement. Should any discrepancy, omission, or erroneous calculation be detected subsequent to this final clearance, administrative and financial accountability will be fixed on the concerned Pay & Accounts Office (PAO)/CCA/CA responsible for the of verification.
- Upon issuance of the Certificate of Correctness of Pay, no recovery of any nature may be effected from the employee in respect of the period covered by the certificate. Any loss to exchequer due to wrong fixation etc. may be recovered from the office who has approved the issue of such certificate.
4. This has the approval of Competent Authority.
Digitally signed by
AVINASH KANTHARAJ NILANKAR
Director
To,
All Secretaries and Financial Advisors of Ministries / Departments.
Click here to view/download PDF
COMMENTS